A financial planner is a professional who helps people organize their finances and make informed decisions about their short- and long-term financial goals. Depending on their qualifications and services, a financial planner may help with budgeting, debt management, saving, retirement, insurance, investments, and financial risk.
So, what does a financial planner do in practice? They assess your financial situation, help prioritize competing goals, and develop recommendations that connect everyday money decisions with your future plans. The services they provide depend on the scope of the engagement, and not every planner offers every service.
This guide explains a financial planner’s responsibilities, how financial planners differ from financial advisors, what their services may cost, and how to evaluate their qualifications, fees, and fiduciary responsibilities before hiring one.
What Is a Financial Planner?
A financial planner is a professional who helps individuals and families understand their financial situation, set realistic goals, and make informed decisions about their money. Depending on their qualifications and the services they provide, a financial planner may help with budgeting, debt management, saving, retirement planning, insurance, investments, and financial risk.
Unlike advice focused on a single financial product or investment, comprehensive financial planning considers how different money decisions affect one another. For example, paying down debt, building an emergency fund, and saving for retirement may compete for the same monthly income. A financial planner can help evaluate these priorities and develop a strategy that connects everyday financial choices with longer-term goals.
The term financial planner does not automatically guarantee a particular qualification, service, or professional standard. Some professionals offer comprehensive planning, while others focus on specific areas or provide investment management. Before hiring one, check their credentials, services, compensation, and the responsibilities covered by your agreement.
What Does a Financial Planner Do in a Comprehensive Plan?
At one point, I had budget shortfalls and struggled to manage my own finances. What helped was not a magical investment choice, but a clearer way to see the whole picture and decide what came first. A certified financial planner may bring a similar structure through education, experience, and ethics—but you should verify the professional’s credentials and services rather than trusting the title alone.
A comprehensive financial plan may examine the following areas:
- Financial position and cash flow: Reviewing income, expenses, savings, assets, liabilities, and regular cash-flow patterns to understand where your money is going.
- Goals, priorities, and planning assumptions: Identifying financial goals, ranking them by urgency and importance, and considering factors such as time horizon, inflation, income, and expected returns.
- Debt, savings, and investments: Evaluating debt repayment, emergency savings, investment choices, and how available resources can support different goals.
- Retirement and risk management: Considering retirement needs, insurance coverage, and other financial risks that could affect your plans.
- Coordination with other professionals: Working with a tax professional, CPA, estate attorney, or another specialist when a recommendation requires expertise outside the planner’s role.
These areas often overlap, but they are not automatically included in every engagement. Can a financial planner help with investments? Often, yes—but investment guidance is only one part of financial planning. A planner may provide comprehensive planning, a focused review, or investment management only. Confirm which services are included and whether the professional is also an investment adviser.
The CFP Board explains different types of financial planning services, which can help you understand what a professional may offer before you agree to work together.
What Does a Financial Planner Do After Delivering the Plan?
A financial plan is useful only when its recommendations can be translated into practical decisions. That is why a financial planner’s work may extend beyond preparing a written document. Depending on the agreement, the professional may help you understand the next steps, coordinate implementation, and review your progress over time.
Ongoing support may include:
- Implementation support, if included: Helping organize next steps, coordinate with an investment professional, or communicate with a tax specialist.
- Clarifying responsibilities: Explaining recommendations and helping you understand what actions are needed, while making clear who is responsible for carrying them out.
- Progress reviews: Reviewing whether your actions remain aligned with your goals and identifying areas that may need attention.
- Adjustments when circumstances change: Revisiting recommendations after major life events, such as marriage, having children, changing careers, approaching retirement, or experiencing a significant change in income.
- One-time or ongoing planning: A one-time engagement may end after the plan is delivered, while an ongoing relationship may include regular meetings, updates, and implementation support.
The practical lesson is simple: never assume that monitoring is included. Ask who will implement the recommendations, what the planner will monitor, how often reviews will occur, and what changes will trigger an update. The CFP Board’s seven-step process identifies implementation, monitoring, and updating as distinct responsibilities that should be clearly defined. Read the CFP Board’s process guide.
What Is a Financial Plan?
A financial plan is a structured framework that connects your current financial situation with your goals and the actions needed to work toward them. Rather than predicting exactly what will happen, it documents your priorities, recommendations, assumptions, and next steps.
In practical terms, a financial plan helps answer four questions: Where do you stand financially? What are you trying to achieve? What choices could help you get there? And what should happen next?
Financial plan output | What it usually includes |
|---|---|
Current financial snapshot | Your assets, liabilities, income, expenses, and present cash-flow position |
Prioritized goals | Your financial goals arranged by importance, timing, and feasibility |
Recommendations and underlying assumptions | Practical recommendations based on assumptions about inflation, returns, income, taxes, and timing |
Action steps and responsible parties | What must be done, by whom, and within what timeframe |
Review arrangements, if agreed | The timing, scope, and responsibilities for future reviews and updates |
Hypothetical example: Suppose you have a limited monthly surplus and three competing priorities: building an emergency fund, paying down expensive credit-card debt, and increasing retirement contributions. A financial planner may help compare the risks and benefits of each sequence, including explaining retirement options such as a 401(k) and answering related questions like what is a 401(k), instead of treating every goal as equally urgent. The final recommendation should explain the trade-offs, assumptions, action steps, and person responsible for each decision.
The most useful plan is not necessarily the longest document. It is the one that turns scattered accounts and financial concerns into clear priorities and manageable actions. Before signing, confirm the planner’s service scope, whether implementation is included, and whether future monitoring forms part of the agreement.
Financial Planner vs Advisor: What Is the Difference?
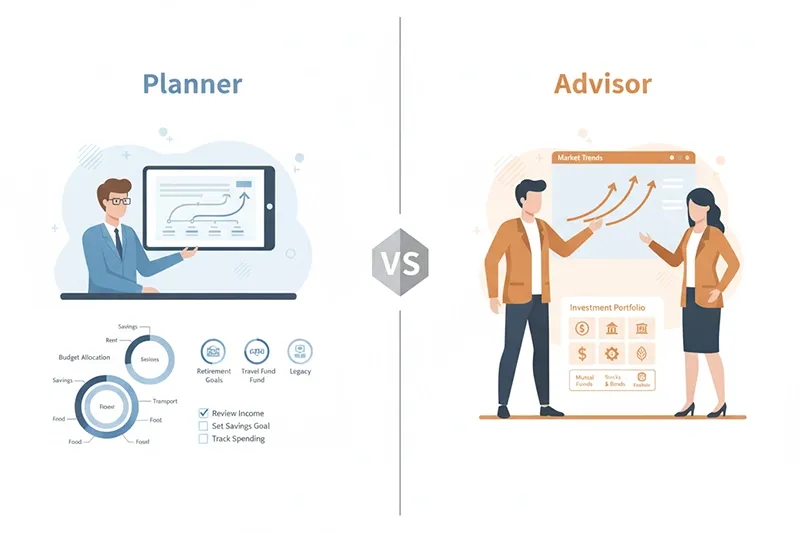
People often treat financial planner and financial advisor as interchangeable titles, yet they can describe different service focuses. A financial advisor is a broad public-facing term, while financial planning usually coordinates several parts of a person’s financial life. In this financial planner vs advisor comparison, ask what services and obligations apply—not which title sounds better. Think of the Organized in Life principle: connected decisions are easier to manage.
What Is a Financial Advisor, and Are Planners Advisors?
I once thought a financial planner mainly studied stock charts. That changed after I experienced budget shortfalls and struggled to manage my finances. A planner can connect cash flow, debt, savings, retirement, insurance, and investment choices. So, what is a financial advisor? It is a broad label. Are financial planners financial advisors? Often, yes—the roles overlap, although not every planner is an investment adviser. Neither title proves qualifications, registration, scope, or fiduciary status; neither is automatically better.
Area | Financial Planner | Financial Advisor |
|---|---|---|
Typical focus | Coordinated goals and comprehensive financial planning | Broad advice, often involving investments or financial products |
Potential services | Cash flow, debt, retirement, risk management, and investing | Investment management, insurance, retirement, or financial planning |
What to verify | Credentials, scope, fees, implementation, and review arrangements | Registration, compensation, services, conflicts, and applicable standards |
What Is a Fiduciary Financial Advisor?
A fiduciary financial advisor is a professional who must place the client’s interests first within the applicable relationship and governing standard. That does not mean conflicts of interest disappear; conflicts may still exist and should be disclosed, managed, or avoided as required. CFP Board standards apply to CFP professionals, while the legal fiduciary framework for investment advisers comes from securities law and SEC interpretation. Ask what standard applies, when it applies, and what disclosures you will receive.
How Much Does a Financial Planner Cost?
When you work with a financial planner, you should understand how they charge for their services. There is no fixed answer to “How much do you pay a financial advisor?” Costs depend on your goals, financial situation, the services you need, and whether you want one-time advice or ongoing support.
Before agreeing, ask about the total cost, included services, and any additional expenses. If you prefer to manage your finances yourself, learning how to create a financial plan can help you organize your goals and understand what you need before deciding whether professional support is necessary.
Hourly, Flat, Ongoing, and Asset-Based Fees
Financial planning costs can take several forms, depending on the type of engagement:
- Hourly Advice
You pay only for the time spent advising you.
This may suit people who need professional guidance on one specific issue, such as creating a budget, managing debt, or prioritizing financial goals. - Fixed-Price Planning Projects
You pay one agreed fee for a complete and clearly defined financial plan.
This may suit people who want a comprehensive review of their finances but do not need to work with a planner on an ongoing basis. - Retainers or Subscription Arrangements
You make a recurring monthly, quarterly, or annual payment for continued access to the financial planner.
This may suit people who want their plan reviewed and updated regularly as their income, expenses, or priorities change. - Percentage-of-Assets-Under-Management Fees
The planner charges a percentage of your invested assets for managing them.
This model is more common in long-term investment management relationships. For example, a hypothetical 1% annual fee on 250,000wouldequal250,000 would equal 250,000wouldequal2,500 per year. This is only an illustration, not a market average or price quote. - Commissions, Where Applicable
Under some arrangements, the planner receives compensation from selling financial products, such as insurance or mutual funds.
This model requires careful attention to possible conflicts of interest. Ask whether commissions apply, how they are calculated, and whether separate product or account expenses could increase your total cost.
Fee-Only vs. Fee-Based: What Are You Paying For?
A fee-only financial planner receives compensation from client fees rather than sales commissions. Fee-only professionals may charge hourly, flat, subscription, retainer, or AUM-based fees. A fee-based planner may combine client fees with commissions from financial products. According to CFP Board and NAPFA guidance, the label alone does not remove the need to review conflicts, disclosures, and fiduciary responsibilities. From my own budgeting experience, separating essential expenses from long-term goals helped me assess financial advice more clearly and make decisions with less pressure.
When Might You Need a Financial Planner?
Many people do not start looking for a financial planner because of one dramatic life event. More often, the need begins with a difficult decision: buying a home or car, getting married, approaching retirement, receiving an inheritance, managing a major income or family change, or balancing competing financial priorities. As finances become more complex, What Is Life Management can also include building a practical plan instead of making important decisions without guidance.
Do You Need to Be Wealthy, or Can You Plan on Your Own?
You do not need to be wealthy to benefit from financial planning, and there is no universal minimum asset level. Requirements vary by provider and service. Some planners offer hourly advice or fixed-price planning projects, so a specific question may call for a limited engagement rather than ongoing investment management. If your finances are straightforward, you may manage them independently. In my experience, a simple monthly review was easier to maintain than several disconnected budgeting tools.
Practical Tip: Before paying for advice, write down the three financial decisions you need help making. Use that list to compare each planner’s proposal, scope, fees, and expected deliverables.
This section follows the service and payment guidance discussed by CFP Board in Types of Services and Paying Your Advisor.
How to Choose a Financial Planner
Choosing a financial planner is less about finding the most impressive title and more about matching the advisor’s expertise, services, compensation, and communication style to your decision. A good choice should clarify trade-offs, not push a product. In practical terms, this is part of What Is Life Management: aligning money decisions with the life you want, while understanding exactly what your financial planning relationship will and will not include.
- Define the problem and the scope of help. Decide whether you need a full financial plan, retirement planning, debt guidance, inheritance advice, insurance analysis, investment management, or help with one specific decision. CFP Board distinguishes financial advice for individual issues from broader financial planning. A focused need may suit hourly or fixed-price advice, while growing complexity may justify ongoing support. This helps you avoid paying for services you do not need.
- Check qualifications and fiduciary responsibilities. Ask whether the professional is a CFP® professional, which financial planning services they provide, and whether they act as a fiduciary throughout the relationship or only for specific work. NAPFA’s Fiduciary Standard emphasizes care, loyalty, competence, transparent compensation, and clear engagement terms. A credential can be valuable, but it should not replace questions about conflicts of interest and client responsibilities.
- Review the compensation model in writing. Ask whether the professional is fee-only or fee-based, and whether charges are hourly, flat, retainer, subscription, AUM-based, or commission-based. CFP Board advises clients to understand how an advisor is paid, while NAPFA defines fee-only compensation as payment directly from clients without sales commissions. Request minimums, product expenses, account fees, and a realistic total cost before signing.
- Interview at least two financial planners before choosing one. Ask who will handle your account, how often reviews occur, whether the planner helps implement recommendations, and how conflicts are disclosed. Compare proposals by scope, deliverables, responsiveness, and communication—not only by the lowest fee. In my own budgeting experience, clear priorities made financial decisions easier; an advisor who explains trade-offs calmly is often more useful than one who hides behind jargon.
- Read the agreement carefully and test whether the relationship feels practical. Confirm cancellation terms, privacy, account access, review frequency, reporting, service changes, and written conflict disclosures. Before signing, write down the three financial decisions you need help making and use them to compare each proposal. If a financial advisor cannot explain the fee in plain language, reconsider. Good financial planning should clarify your next steps, not create another spreadsheet maze.
Conclusion
Choosing a financial planner is not about handing over control of your money; it is about gaining a clearer framework for decisions. Understanding how much a financial planner costs helps you compare hourly advice, fixed-price planning, retirement planning, and ongoing investment management. In my experience, clear priorities make budgeting and long-term financial planning more manageable. Review services, fees, qualifications, and fiduciary responsibilities. The right planner should explain trade-offs plainly, respect your goals, and turn financial uncertainty into confident next steps.
Was this article helpful?
Next Article
Artificial Intelligence Applications in Daily Life: 10 Real-World Examples
Comments(0)
Be the first to leave a comment.